Food Vendor Insurance for Texas Fairs, Markets, and Festivals
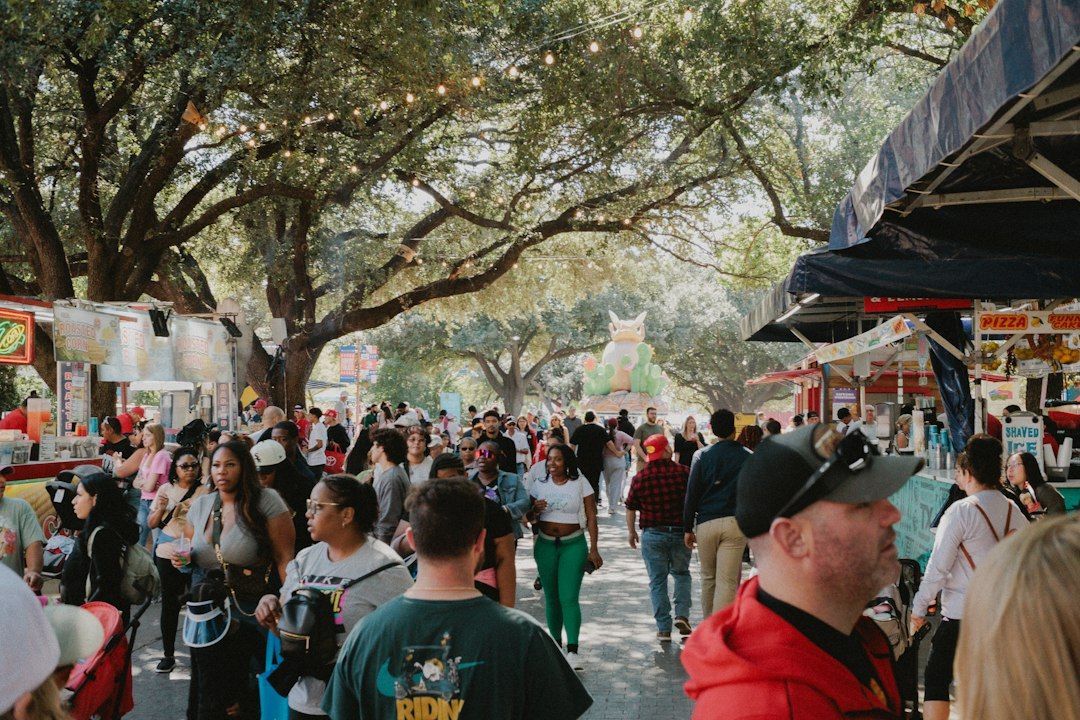
Texas is famous for its legendary gatherings, from the massive Houston Livestock Show and Rodeo to the sprawling State Fair of Texas, plus thousands of local farmers markets and music festivals. For culinary entrepreneurs, these events offer a rare chance to reach hungry crowds, test new menu items, and grow a loyal customer base.
The Thriving Texas Event Scene and Your Food Business
Texas is famous for its legendary gatherings, from the massive Houston Livestock Show and Rodeo to the sprawling State Fair of Texas, not to mention thousands of local weekend farmers markets and music festivals across the state. For culinary entrepreneurs, these events offer an unparalleled opportunity to reach hungry crowds, test new menu items, and grow a loyal customer base. However, before you can fire up the grill or start serving your artisan treats, there is one non-negotiable hurdle you must clear. You must prove you have the correct insurance coverage.
As seasoned insurance professionals at Farmers Insurance - The West Agency, we have spent decades helping Texas businesses navigate the complexities of commercial risk. We know that event organizers, municipal governments, and private venue owners are highly protective of their patrons and their property. Consequently, they impose strict requirements on what your food vendor insurance must entail. They cannot afford to take chances on vendors who are underinsured.
In this comprehensive guide, we will outline the specific liability and product-related coverages that Texas venues commonly require, explain why these protections are vital, and help you ensure your mobile food business is fully prepared for your next big event.
The 2026 Texas Regulatory Landscape for Mobile Vendors
Operating a mobile food business in Texas has seen significant regulatory shifts recently, opening up more opportunities for vendors to travel across the state. One of the most important updates took effect on July 1, 2026, when Texas House Bill 2844 transitioned mobile food vendors to a unified, statewide license issued by the Texas Department of State Health Services (DSHS).
Before this legislation, a food truck traveling from Houston to Austin and then up to Dallas would need to secure separate health permits and pass individual physical inspections in every single county. This long-awaited change eliminates that administrative headache, allowing vendors to participate in far more festivals statewide under one central health license.
However, it is crucial to understand that while health permitting has been centralized, insurance requirements have not. Event organizers, municipal parks departments, and private venue owners still independently set their own insurance minimums as a condition of participation. Even with a shiny new statewide DSHS license in hand, you cannot simply roll your food truck or set up your pop-up tent on festival grounds without providing a valid Certificate of Insurance (COI) that meets the host host's exact standards.
Event hosts carry substantial risk when they invite thousands of people onto their property. If a patron gets sick from a vendor's food or trips over a vendor's extension cord, the venue itself is almost always named in the ensuing lawsuit. To mitigate this, they transfer the risk back to the vendors. Understanding the specific Texas small business insurance basics that venues demand will prevent you from being turned away at the gates on opening day.
Essential Liability Coverages Venues Demand
When an event organizer sends you their vendor packet, the insurance section is usually detailed, highly specific, and completely non-negotiable. Here are the core coverages you will be expected to carry to satisfy their requirements.
The Foundation: A Commercial General Liability Policy
The cornerstone of your protection, and the first thing any venue will check, is your general liability policy. In some international markets, this is referred to as business public liability insurance, but here in Texas, it is universally known as Commercial General Liability.
This coverage protects you and the event host against claims of third-party bodily injury and property damage arising from your daily operations. For a busy food vendor, this could involve a variety of common accidents:
- A customer tripping over an anti-fatigue mat or power cord near your serving window.
- Hot cooking oil or boiling water accidentally splashing onto a patron in a crowded walkway.
- A sudden Texas windstorm blowing your heavy canopy tent into a parked car or a neighboring vendor booth.
- A grease fire in your mobile kitchen spreading and damaging the venue's historic pavilion. Most Texas festivals and markets require a minimum of $1,000,000 per occurrence and $2,000,000 in general aggregate coverage. Major events that draw hundreds of thousands of attendees may require even higher limits or an additional commercial umbrella policy to provide an extra layer of financial padding.
The Critical Component: Products and Completed Operations
While general liability covers physical accidents around your booth, what happens if the food itself causes harm? This is where Product Liability, often bundled within the commercial general liability policy as "Products-Completed Operations", becomes absolutely essential.
For culinary professionals, product liability is arguably the most significant daily exposure you face. It responds to claims involving:
- Foodborne Illnesses: Outbreaks of E. coli, salmonella, or listeria that health departments trace back to your ingredients or storage methods.
- Allergic Reactions: Severe medical emergencies caused by kitchen cross-contamination or undeclared allergens like peanuts, dairy, or shellfish.
- Foreign Objects: A customer chipping a tooth on an unexpected bone fragment or a stray piece of packaging that accidentally ended up in their meal. Just as a local furniture builder might rely on manufacturing and product liability insurance basics for Texas makers, food vendors must have robust product liability coverage built specifically for consumables. Event organizers know that food poisoning claims can rapidly spiral into massive legal battles involving multiple victims, so they will strictly verify that your policy includes comprehensive products coverage without restrictive exclusions.
The Paperwork: Additional Insured Endorsements
Simply having an active insurance policy is not enough for most venues. You must explicitly extend your coverage to the event host. Venues will almost always require you to add them to your policy as an "Additional Insured."
This legal endorsement means that if the venue is sued because of something your food business did wrong, your insurance policy will step in to defend the venue and cover the damages, rather than the venue having to rely on their own insurance. Without this specific endorsement listed clearly on your Certificate of Insurance, you will simply not be permitted to operate on their grounds.
Vehicle and Employee Coverages
If you operate a motorized food truck or pull a heavy food trailer, venues will require proof of commercial auto insurance for Texas small businesses. Personal auto policies routinely exclude business operations. An accident while towing your custom food trailer through a crowded fairground would likely result in a denied claim on a personal policy.
Furthermore, if you bring employees to help run the booth, many large events will mandate that you provide proof of workers compensation insurance. Even though the state of Texas allows many private employers to opt out of the workers compensation system, private venues and large festivals often require it to ensure they are not held liable if your cook or cashier suffers an injury on the job.
Navigating Specialized Risks vs. General Business Coverages
A large Texas festival involves hundreds of different businesses working closely together, and the insurance needs vary wildly among them. For example, the production crew setting up the main concert stage will be busy gathering contractors liability insurance quotes to cover heavy machinery, rigging, and structural risks. Meanwhile, an entertainment company providing inflatable slides or obstacle courses will specifically need bounce house liability insurance to cover the extremely high risk of child injuries.
As a food vendor, your risks are distinctly culinary and customer-facing. It can be incredibly tempting to search online for cheap small business liability insurance just to quickly check the box for the event application. However, we strongly caution against this bare-minimum approach.
Bargain-basement policies often contain hidden exclusions that can prove disastrous in the real world. For instance, some cut-rate policies might quietly exclude coverage for communicable diseases or bacterial infections, meaning a food poisoning claim might be completely denied. Others might charge exorbitant hidden fees every time you need to generate a new Certificate of Insurance with an Additional Insured endorsement, effectively wiping out any upfront savings if you attend multiple festivals a year.
When you purchase insurance for Texas events, venues, and mobile food vendors, you need a policy designed expressly for the food service industry. A localized, specialized approach ensures that when a strict venue requires highly specific wording on a COI, your agent understands the request and can provide the documentation quickly and accurately.
Navigating Advanced Venue Requirements
As you graduate to larger, more lucrative events like the Austin City Limits Music Festival or the San Antonio Rodeo, you will encounter more complex insurance terminology in your vendor agreements. Being prepared for these requests will make you a preferred vendor in the eyes of organizers.
One common requirement is a "Waiver of Subrogation." Subrogation is a process where your insurance company, after paying out a claim on your behalf, sues a third party who they believe was actually at fault to recover their money. By signing a waiver of subrogation, your insurance company agrees not to sue the venue, even if the venue's negligence partially contributed to the incident.
Another frequent demand is "Primary and Non-Contributory" language. This simply means that if a claim occurs, your insurance policy must pay out first (primary) and will not ask the venue's insurance policy to chip in to help cover the costs (non-contributory).
These clauses are standard in the large event industry, but many basic, off-the-shelf insurance policies do not include them automatically. Having an expert review your vendor contracts ensures your policy is properly endorsed before you pay your non-refundable booth fees.
Checklist for Getting Approved at Texas Festivals
To ensure a smooth approval process for your next market or festival, we recommend following this straightforward checklist well in advance of the event date.
- Review the Vendor Packet Immediately: As soon as you are accepted into a festival, read the insurance requirements section thoroughly. Look for required liability limits, specific Additional Insured wording, and any demands for a waiver of subrogation.
- Contact Your Agent: Send the vendor packet directly to your insurance agent. Working with a local Farmers Insurance agent in Texas means you have a partner who can translate the venue's legal jargon into a clear action plan.
- Request the COI Promptly: Do not wait until the week of the event to request your Certificate of Insurance. Venues often have strict processing deadlines, and missing them can result in forfeited booth space.
- Maintain Your Statewide License: Ensure your new statewide DSHS mobile food vendor license is current and that you have a physical or digital copy ready for health inspectors on the day of the event.
- Prepare Your Staff: Ensure your team understands and follows rigorous food safety protocols. Insurance is your vital financial safety net, but excellent food handling practices are your first line of defense against product liability claims.
Securing Your Financial Future in the Texas Food Scene
Serving food at Texas fairs, markets, and festivals is an exciting and profitable venture, but it comes with immense responsibility. As the regulatory landscape continues to evolve, highlighted by the 2026 shift to statewide DSHS licensing for mobile units, the foundational need for robust insurance remains completely unchanged. Venues and cities will always prioritize public safety and financial protection, requiring you to carry comprehensive general liability and product liability coverages.
By investing in a high-quality policy tailored specifically to food service, rather than settling for generic and restrictive coverage, you protect your livelihood and make the event approval process seamless. When your insurance is perfectly in order, you can stop worrying about compliance and focus entirely on what you do best. You can focus on delivering incredible food and memorable experiences to your loyal Texas customers.
Farmers Insurance - The West Agency
Ready to take the next step? Contact us today for personalized assistance and discover how we can help you achieve your goals. Your success is our priority, and we are here to support you every step of the way.
Whether you are gearing up for a bustling local farmers market or a massive multi-day music festival, our team at Farmers Insurance - The West Agency is here to ensure you have the exact coverage the venues demand. With over 30 years of experience protecting Texas businesses, we make securing the right commercial coverage simple, reliable, and stress-free. Let us handle the complexities of Certificates of Insurance and specialized contract endorsements so you can focus entirely on your culinary passion. Reach out to get a custom quote today and experience the dedication, deep expertise, and customized solutions of a truly local Texas insurance agency.
By Mike West & Team · Published 7/10/2026