
Insurance Essentials for Texas Wedding Photographers and Videographers
The Texas wedding industry is a fast paced, high stakes environment where creativity meets precise logistics. From historic estates in Houston to sprawling Hill Country ranches, capturing a couple's special day demands immense skill, preparation, and reliable gear amid rising risks.
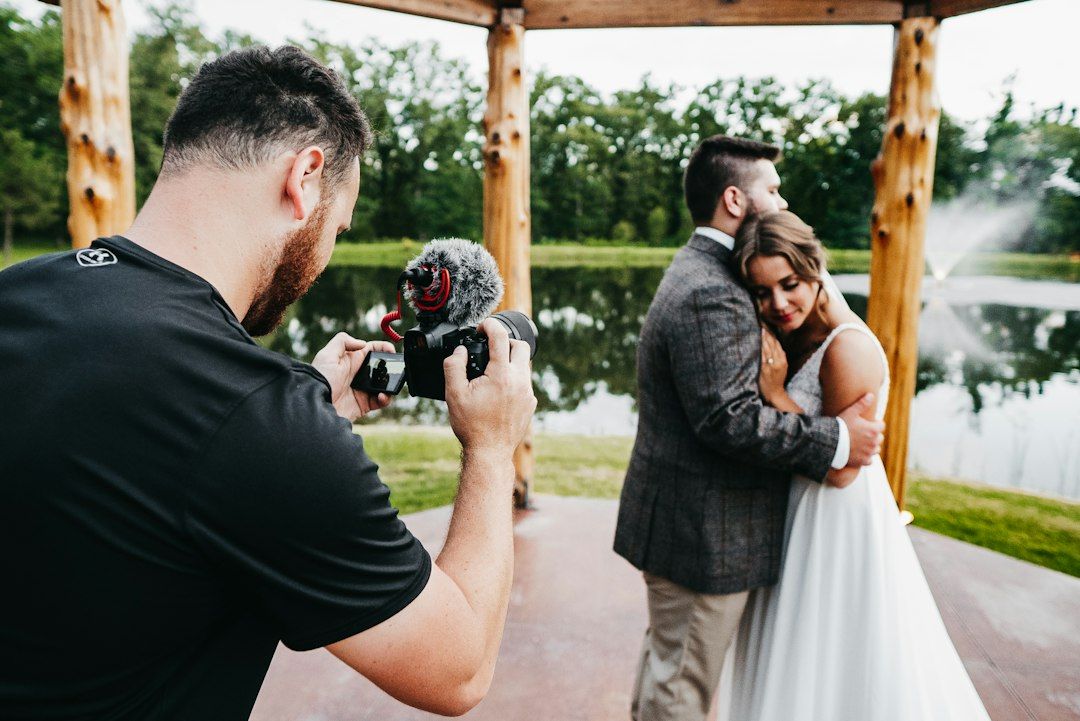
Capturing the Big Day: Why Proper Coverage Matters More Than Ever
The Texas wedding industry is a fast paced, high stakes environment where creativity meets precise logistics. From historic estates in Houston to sprawling ranches in the Hill Country, capturing a couple's special day requires immense skill, preparation, and reliable gear. However, as the industry grows and events become more elaborate, the risks associated with wedding photography and videography have never been higher.
As seasoned insurance professionals serving Texas businesses, we have seen firsthand how an unexpected mishap can threaten a creative professional's livelihood. In places like Dripping Springs, widely recognized as the Wedding Capital of Texas, the sheer volume of celebrations means venues run incredibly tight ships. Venue owners are hyper aware of their liability exposures, and they increasingly shift that responsibility onto the vendors working on their property.
If you are a creative professional in this space, you are no longer just an artist with a camera. You are an independent business owner operating in highly trafficked, emotionally charged environments. Understanding your specific risks, navigating venue requirements, and securing the right coverage are foundational steps to building a sustainable and profitable wedding business.
Overview: The Changing Landscape of Texas Weddings
The environment for wedding professionals in Texas has shifted significantly over the past few years. Couples are investing heavily in personalized, highly documented experiences. According to recent industry data, non-traditional venues like ranches, refurbished barns, and local breweries now account for approximately 45 percent of Texas weddings. While these locations offer stunning backdrops, they also present unique challenges.
Outdoor environments introduce unpredictable weather, uneven terrain, and limited power sources. Historic venues often feature delicate architecture, antique furnishings, and strict preservation rules. Because of these factors, venue owners have become incredibly strict about who they allow on their property. The days of showing up with a camera and a smile are long gone. Today, the "No COI, No Entry" rule is strictly enforced across the state. A Certificate of Insurance, or COI, is official documentation proving that your business carries adequate liability coverage.
For wedding creatives, the financial stakes are also higher than ever. The equipment required to produce modern, cinematic wedding galleries is a massive investment. A standard professional videography setup today, complete with full frame mirrorless cameras, premium lenses, professional audio recorders, gimbals, and drones, can easily exceed twenty thousand dollars in value. If that gear is stolen from a vehicle during a reception or severely damaged by a sudden Texas downpour, the out of pocket replacement costs could be devastating to a small business.
This combination of strict venue requirements and high value equipment makes comprehensive business insurance for photographers an absolute necessity. Relying on a standard homeowners policy or a generic business plan will almost certainly leave dangerous gaps in your protection. You need specialized coverage designed for the reality of live events.
Key Aspects of a Complete Wedding Professional Insurance Plan
Building a resilient safety net for your creative business involves layering several specific types of coverage. Each policy serves a distinct purpose, stepping in to protect you from different angles of risk on a wedding day.
General Liability Insurance
General liability is the foundation of any commercial insurance package. This is the exact policy venues are looking for when they request a Certificate of Insurance. General liability protects your business if your operations cause third party bodily injury or third party property damage.
Imagine you are setting up off camera flash units for the reception dance floor. A guest, caught up in the excitement of the music, trips over your light stand and suffers a severe injury requiring emergency medical attention. Alternatively, imagine dragging a heavy equipment case across the floor of a historic venue and leaving a deep, unrepairable scratch on the original hardwood. In both scenarios, the injured guest or the property owner could file a claim against you.
Your photographer liability insurance would step in to cover the legal defense fees, settlements, and medical payments associated with the incident. Without this coverage, you would be personally responsible for those costs, which could easily bankrupt a small studio.
Inland Marine and Equipment Protection
Many creatives mistakenly believe that their standard commercial property insurance will cover their gear. However, commercial property insurance typically only covers items while they are physically located at your primary business address. Since wedding professionals are constantly on the move, you need a policy that travels with you.
Inland marine insurance, often referred to as equipment coverage, protects your cameras, lenses, laptops, and lighting gear while it is in transit or on location. Whether your gear is stolen from your trunk while you are shooting engagement portraits in downtown Dallas or a guest accidentally spills a drink directly onto your camera body, a robust videographer insurance policy with equipment coverage ensures you can replace your tools quickly and get back to work.
Professional Liability (Errors and Omissions)
While general liability covers physical accidents, professional liability covers financial losses or emotional distress caused by your professional services. Also known as Errors and Omissions insurance, this coverage is critical for wedding vendors because you are dealing with once in a lifetime moments that cannot be replicated.
Consider the nightmare scenario where your memory cards corrupt, your hard drives fail before backup, or a technical glitch causes you to miss the couple's vows entirely. If the couple decides to sue you for breach of contract or emotional distress due to the loss of their wedding media, professional liability insurance will cover your legal defense and any resulting settlements. Even if you did nothing wrong and the lawsuit is frivolous, the cost of hiring an attorney to defend your business can be overwhelming.
Aviation Liability for Drone Operators
Cinematic drone footage has become a standard request for Texas wedding films. If you operate a drone commercially, you are legally acting as an aviator. Standard general liability policies almost universally exclude aviation related incidents. If your drone loses connection and crashes into a parked luxury car or, worse, injures a wedding guest, you need specific aviation liability coverage added to your policy to handle the fallout.
Insights on Navigating Insurance as an Independent Contractor
As independent contractors, wedding photographers and videographers face a unique set of challenges when securing and utilizing their insurance. We regularly speak with creatives who find the process confusing, especially when trying to decipher complex venue contracts.
One of the most common pitfalls we see involves the pursuit of cheap small business liability insurance. When you are just starting out and trying to keep overhead low, it is tempting to jump online and buy the absolute lowest priced policy you can find. However, these cut rate policies are notoriously rigid. They often feature high deductibles, low coverage limits, and strict exclusions that you may not discover until it is time to file a claim.
More importantly, cheap policies often lack the ability to easily add "Additional Insured" endorsements. When a venue asks for a COI, they rarely just want proof that you have insurance. They typically require you to list the venue's legal holding company as an Additional Insured on your policy for the specific dates of the event. This means your insurance will protect the venue if they get sued because of your negligence. Many online, budget tier insurers charge exorbitant fees for each Additional Insured certificate, or they make the process so slow that you risk missing the venue's submission deadline.
When you are comparing contractors liability insurance quotes, you must look beyond the monthly premium. You need to ask potential providers how quickly they can generate a COI, whether there are fees for adding an Additional Insured, and how their claims process works. Working with a dedicated, local agent allows you to secure a policy that actually meets the stringent demands of high end Texas venues.
Furthermore, as your business grows, your risks will evolve. Successful wedding professionals frequently expand their revenue streams by hosting photography workshops, styled shoots, or industry networking mixers. If you decide to rent a studio space in Austin to host a vendor mixer and you serve complimentary wine or cocktails, you are stepping outside the bounds of your standard photography coverage. In this scenario, you may need to secure event liquor liability insurance to protect yourself from alcohol related incidents. A knowledgeable agent will help you identify these hidden exposures before they become a problem.
The "No COI, No Entry" Action Plan for Wedding Creatives
To ensure seamless operations and avoid stressful weekend emergencies, wedding professionals must integrate insurance compliance directly into their booking and planning workflows. Waiting until the week of the wedding to handle venue requirements is a recipe for disaster.
Implement these best practices into your business operations to stay ahead of the curve.
Ask for Venue Requirements During the Booking Phase
Do not wait for the couple or the wedding planner to send you the venue rules. Make it a standard part of your onboarding process to proactively request the venue's vendor guidelines. High end venues in Texas often have very specific requirements, such as demanding two million dollars in aggregate coverage or requiring primary and noncontributory language on the certificate. Knowing this six months in advance gives you plenty of time to review your policy and request any necessary adjustments.
Streamline Your COI Request Process
Establish a clear system for requesting Certificates of Insurance from your broker. You will need the exact legal name of the venue, their physical address, and any specific wording they require in the description box of the certificate. Having this information organized allows your insurance agent to generate the document quickly and accurately.
Add Insurance Clauses to Your Client Contract
Your contract should clearly outline your insurance capabilities. State that your business is fully insured and that you are happy to provide a standard COI to the venue upon request. However, you should also include a clause stating that if a venue requires excessive coverage limits or unique endorsements that fall outside your standard policy, any additional premium costs required to meet those demands will be billed to the client. This protects your bottom line from unusually demanding venues.
Audit Your Equipment Annually
Wedding creatives constantly buy, sell, and upgrade their gear. A lens you bought three years ago might not be the lens you use today. Schedule an annual review of your equipment schedule. Make sure every new camera body, lens, audio recorder, and lighting unit is properly listed with its current replacement value on your inland marine policy. If you rely on gear that is not listed on your policy, you will not receive a payout if it gets damaged or stolen.
Require Insurance from Your Second Shooters
If you hire second shooters or lighting assistants, you must clarify their insurance status. If they operate as independent contractors, you should require them to carry their own general liability and equipment coverage. Alternatively, if your business structure allows, ensure your policy is designed to cover the actions of temporary employees or subcontractors. A mistake made by a second shooter can easily result in a lawsuit directed at your primary brand. We highly recommend consulting with a professional to ensure your team structure aligns with your coverage.
Conclusion
Photographing and filming weddings is a uniquely demanding profession. You are tasked with balancing intense artistic creativity with high pressure logistics, all while managing thousands of dollars in fragile equipment. In the bustling Texas wedding market, standing out requires more than just a beautiful portfolio. It requires professionalism, reliability, and the foresight to protect your business against the unexpected.
Securing the right coverage goes far beyond checking a box for a venue. It provides you with the peace of mind needed to perform at your highest level. When you know your gear is protected, your liability is covered, and your business is shielded from devastating lawsuits, you can focus your energy entirely on what you do best. Do not let a split second accident jeopardize the business you have worked so hard to build.
Farmers Insurance - The West Agency
Ready to take the next step? Contact us today for personalized assistance and discover how we can help you achieve your goals. Whether you are a solo photographer shooting intimate elopements or a large videography team handling luxury multi day events across Texas, we understand the specific risks your creative business faces.
Our team at Farmers Insurance - The West Agency is dedicated to crafting tailored insurance solutions that fit your exact needs. We make securing certificates of insurance, protecting your expensive gear, and meeting venue requirements simple and stress free. Your success is our priority, and we are here to support you every step of the way. Request a quote online, or reach out to speak directly with our experienced commercial insurance professionals. Your coverage. Our expertise. One stronger agency.
By Mike West & Team · Published 6/25/2026